


If you own a small business, the weeks between now and New Year's Eve are the last real window to change your 2026 tax result. Whether you run a veteran-owned company, a home-based business as a military spouse, or a growing LLC, this year-end tax planning checklist for a small business walks through ten moves we review with clients each fall. It is written for owners filing on the cash method, which is most small businesses. Rules differ by entity type and income, so treat this as a map, not a prescription.

If you served and then started a business, you may have heard that there are veteran owned small business tax credits waiting for you. The truth is more specific. Most of the money comes from what your business does (hiring, payroll, benefits), not from the fact that a veteran owns it. This guide walks through five things veteran business owners ask about most, what each one really does, and where 2026 has changed the picture.

If you're weighing S-corp vs LLC taxes 2026, the first thing to know is that you aren't really choosing between two business types. An LLC is created under state law. An S-corp is a tax election the IRS lets certain businesses make. Plenty of small business owners run an LLC that is taxed as an S-corp, so the question that matters is how your profit gets taxed.

Leaving active duty changes your tax picture fast. Use this military transition tax checklist to handle separation pay, leave and new income correctly.

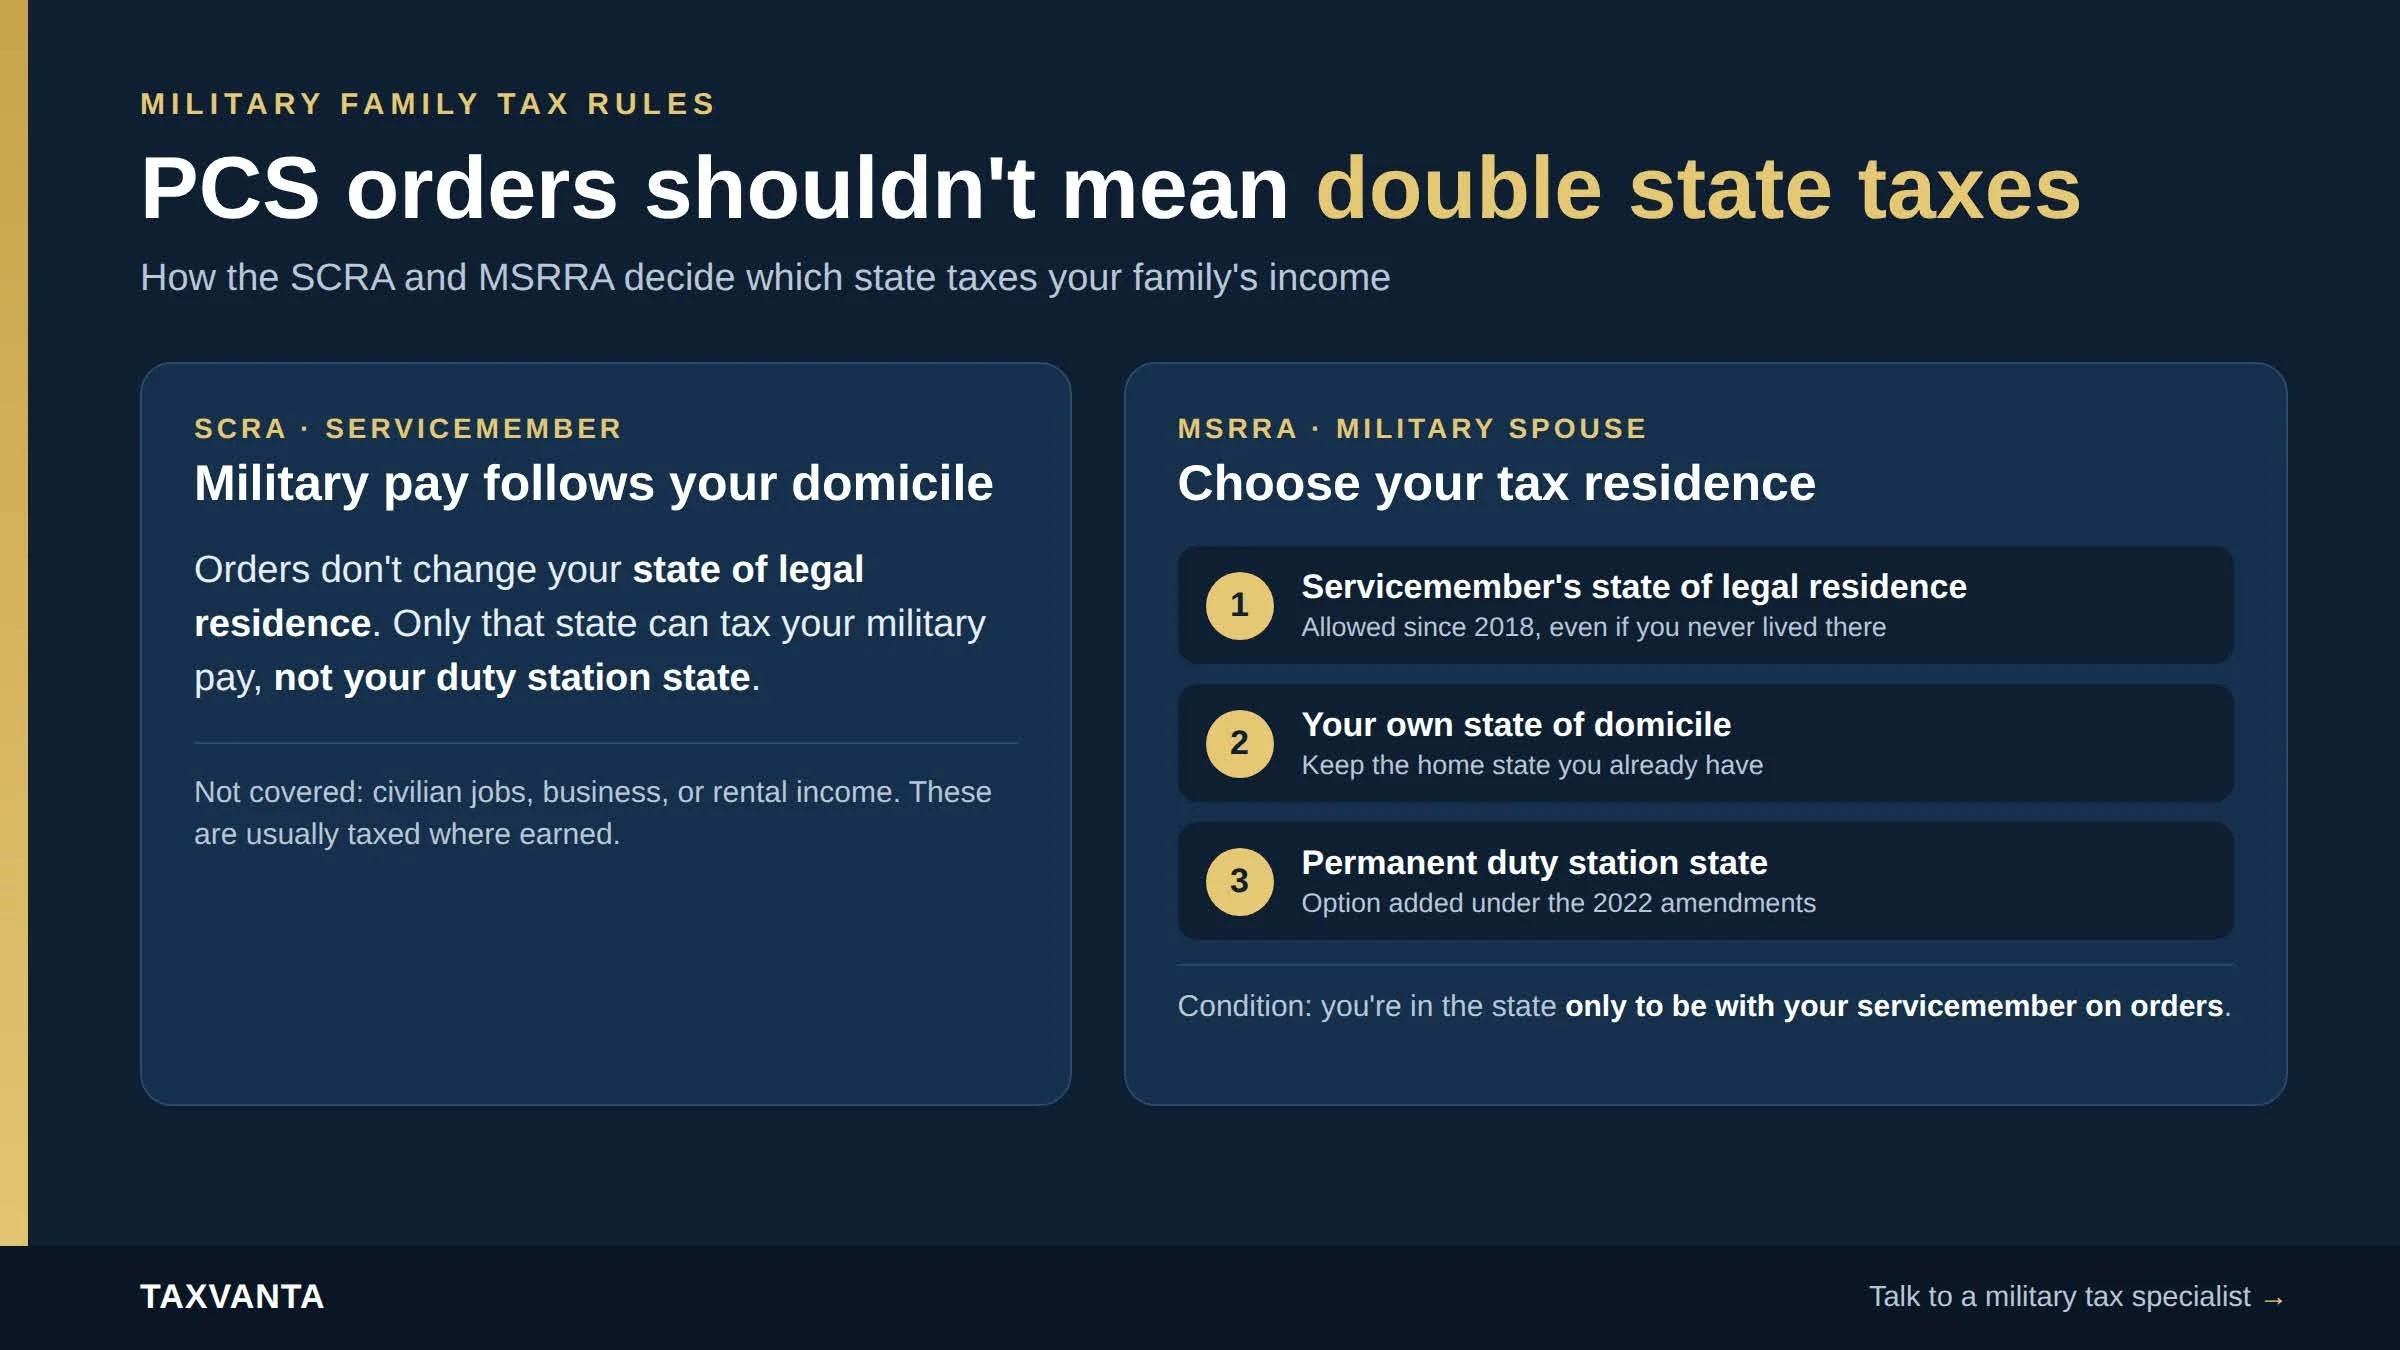
The Servicemembers Civil Relief Act (SCRA) is a federal law that, among other protections, says a servicemember does not lose or gain a state of legal residence for tax purposes just because military orders move them to another state. Their military pay is taxable only by their state of legal residence. The Military Spouses Residency Relief Act (MSRRA) is a 2009 amendment to the SCRA that extends similar protection to military spouses: a spouse who moves to a state only to be with a servicemember on orders can keep their own state of legal residence for tax purposes, and the host state can't tax the spouse's wages earned there.
Put simply: a PCS move doesn't have to change which state you pay income tax to. Here's how the rules work, how they've changed since 2009, and the mistakes that most often lead to double state taxes.
Anyone can legally prepare a tax return for pay as long as they have a PTIN — a preparer tax identification number that takes about ten minutes to get online.
Between VA waivers, CRDP, CRSC, and retroactive rating decisions, it's easy for military retirement income to get taxed incorrectly — usually not because the rules are unclear, but because the paperwork doesn't catch up to a rating change right away.
The One Big Beautiful Bill Act, commonly shortened to OBBBA, is the 2025 federal tax law that extended and expanded major provisions of the 2017 Tax Cuts and Jobs Act. For small business owners, the practical effect is a handful of specific, dollar-and-cents changes to depreciation, the pass-through deduction, R&D cost recovery, and interest expense limits — several of which the IRS has already built into its 2026 inflation-adjusted figures.
Most tax preparers are generalists, and there's nothing wrong with that — most returns don't need a specialist. Military retirement pay isn't like most returns, though. It comes with its own set of rules, forms, and elections that simply don't come up for the average client, which means they don't come up for the average preparer either. If nobody asks, nobody catches them.
Here are five that we see missed most often.
Somewhere between out-processing paperwork, a final PCS, and figuring out what civilian job comes next, taxes are probably not at the top of your mind the year you retire. They should be closer to it than usual, though — because the year you transition out of active duty is one of the most complicated tax years you'll ever file, and it only happens once.
Here's what actually changes.
If you're retiring from the military — or you already have — you've probably noticed that tax advice aimed at "retirees" in general doesn't quite fit your situation. Regular retirement guides talk about pensions and 401(k)s. They rarely mention CRDP, CRSC, or the fact that your retired pay is taxed completely differently depending on which state you happen to live in.
That last part is the one that catches people off guard. Your federal tax bill on military retirement pay is the same no matter where you live. Your state tax bill can range from zero to several thousand dollars a year, for the exact same pension, just because of a zip code.